
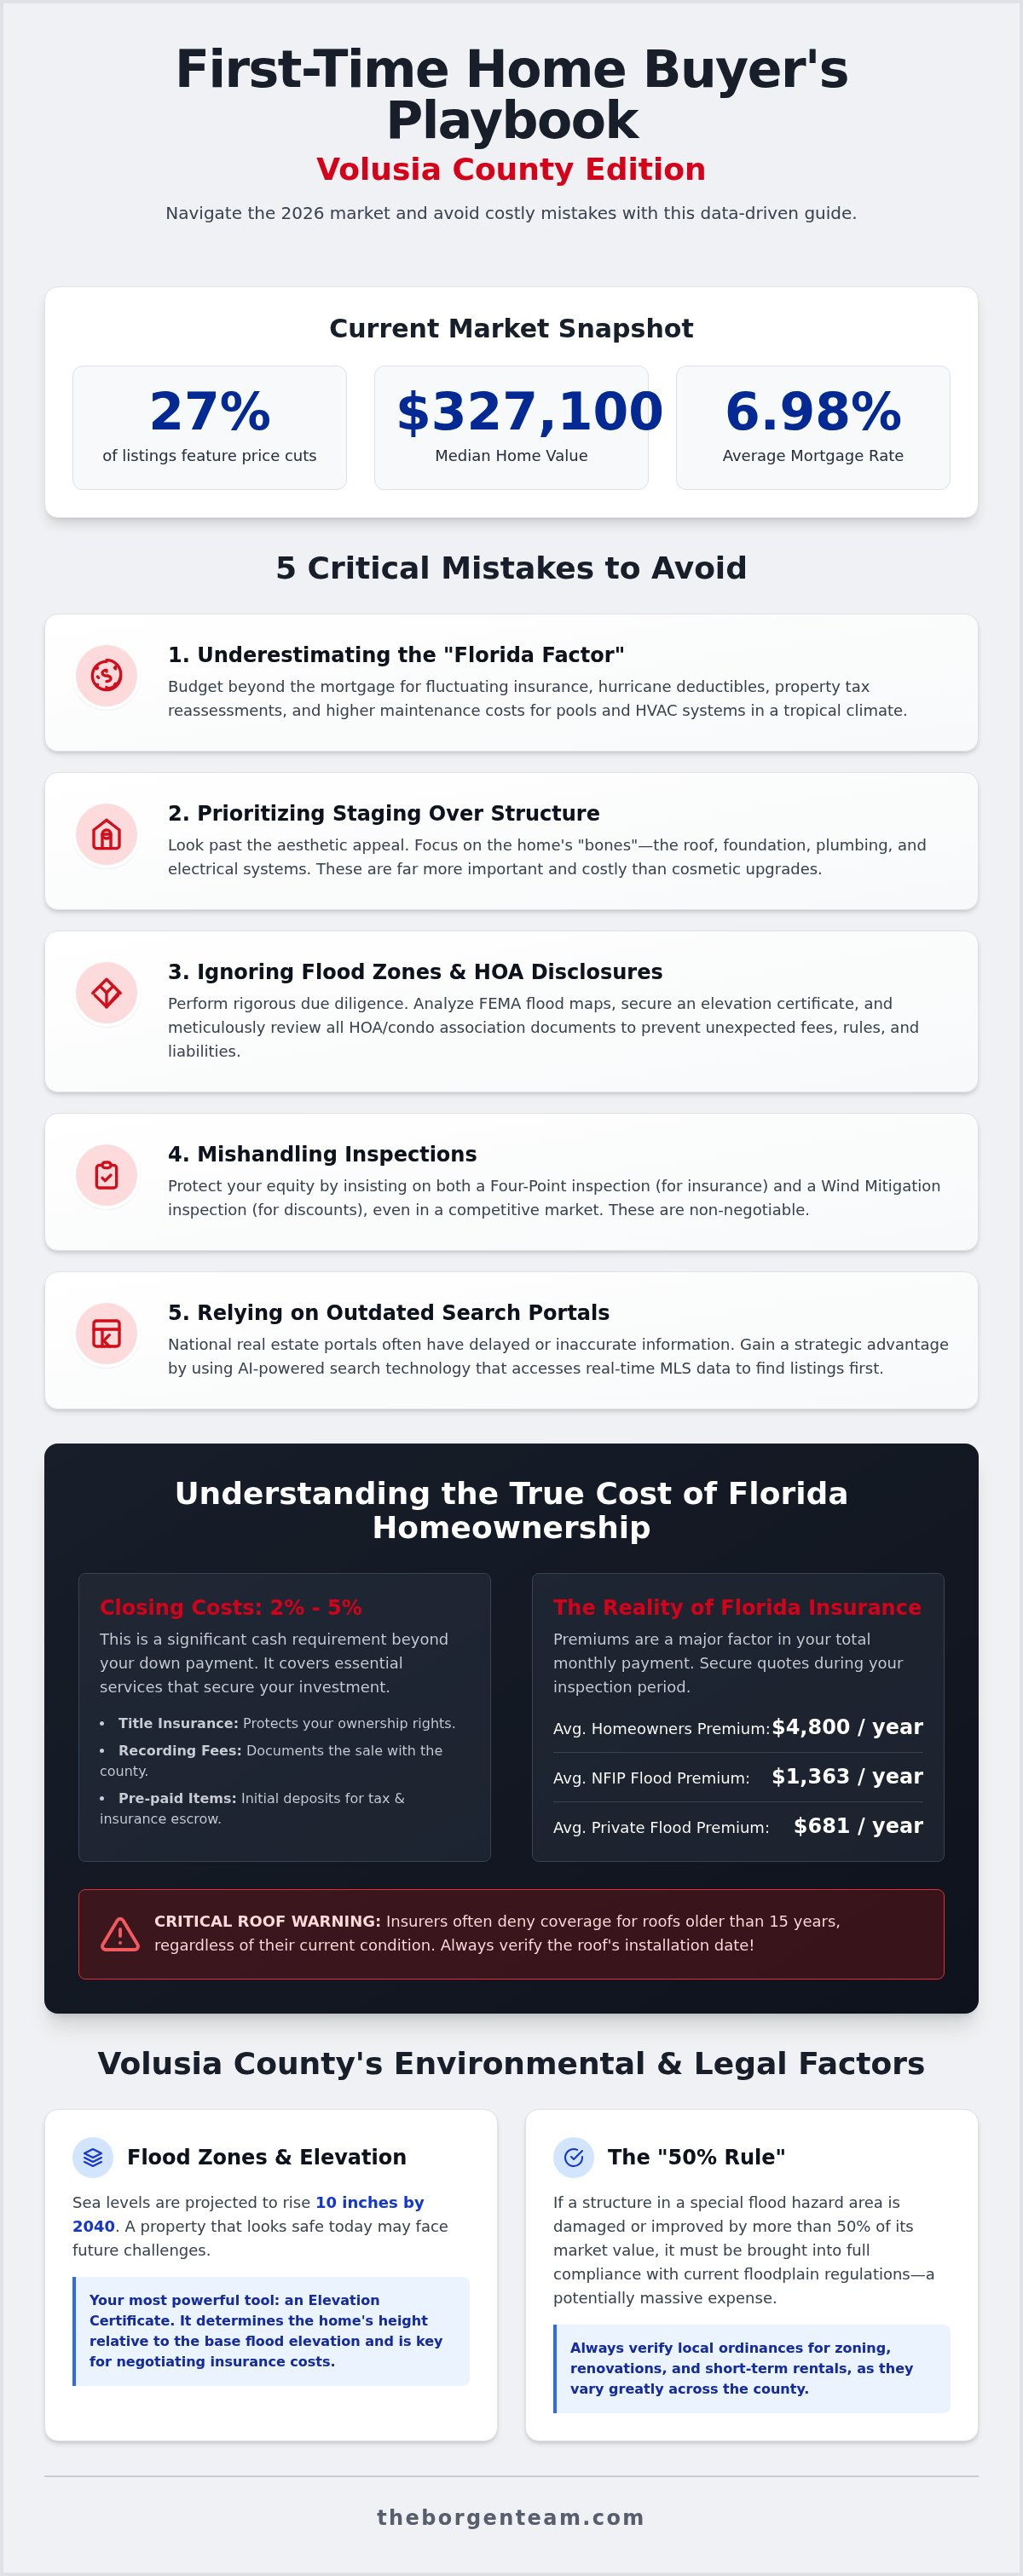
Did you know that 27% of Volusia County listings currently feature price cuts, yet many buyers still overpay because they lack a data-driven strategy? Entering the 2026 market in Daytona Beach or
Dated: September 16 2026
Views: 0
Did you know that 27% of Volusia County listings currently feature price cuts, yet many buyers still overpay because they lack a data-driven strategy? Entering the 2026 market in Daytona Beach or DeLand requires more than just a pre-approval letter; it demands precision. You likely feel the weight of rising flood insurance premiums and the anxiety of missing the right home in a fast-moving environment. It's normal to fear hidden defects or miscalculating the total cost of ownership when the median home value sits at $327,100.
Understanding the critical first time home buyer mistakes to avoid is the difference between a stressful ordeal and a sophisticated investment. This guide promises to equip you with the tools to navigate Florida's complex real estate landscape with total confidence. We'll examine how to use AI-powered search technology to gain a competitive edge. You'll also get a clear preview of local negotiation tactics and the specific financial realities of Volusia County, from homestead exemptions to the latest 6.98% mortgage rates, ensuring your first purchase is a definitive success.
Budgeting for a home in Volusia County involves more than just calculating your principal and interest. Many buyers focus exclusively on the mortgage payment and fail to account for the "Florida Factor." This oversight is one of the most critical first time home buyer mistakes to avoid because it leads to immediate financial strain after closing. In Florida, your monthly escrow can fluctuate wildly based on insurance reassessments and tax adjustments.
Expect property tax "sticker shock" during your second year of ownership. Florida law caps tax increases for existing homeowners, but those protections disappear when a property sells. Your taxes will be based on the new purchase price and current millage rates, such as the 3.2007 General Fund rate set for the 2026-27 fiscal year. Additionally, you must fund maintenance reserves for tropical-specific needs. The intense heat degrades HVAC systems faster than in northern climates; maintaining a pool or lush landscaping requires a dedicated monthly budget that many novices overlook.
Prepare for "cash to close" requirements that extend beyond your down payment. In Volusia County, buyers typically face closing costs ranging from 2% to 5% of the total purchase price. These funds cover essential legal and administrative steps that secure your investment:
Focus on the final settlement statement rather than the sales price. This ensures you have sufficient liquidity to finalize the deal without depleting your emergency savings.
The 2026 insurance market shows signs of stabilization, with some major carriers filing for rate reductions for the first time since 2019. However, premiums in Volusia County still average approximately $4,800 annually. One of the primary first time home buyer mistakes to avoid is neglecting the age of the home's roof. Carriers often deny coverage or cancel policies immediately if a roof is older than 15 years, regardless of its current condition.
Flood insurance is another non-negotiable consideration. Even if your property sits outside a high-risk zone, the risk of flash flooding in coastal Florida makes coverage essential. NFIP policies average $1,363 annually, while private options may offer lower median premiums around $681. Secure these quotes during your inspection period to avoid a budget-breaking surprise at the finish line.
Success in the Florida market requires a deep understanding of the ground beneath your feet. Volusia County features diverse topography, from the riverfronts of Deltona to the shifting dunes of New Smyrna Beach. One of the most expensive first time home buyer mistakes to avoid is failing to analyze the long-term environmental risks of a specific parcel. With sea levels projected to rise by 10 inches by 2040, a property that looks dry today might face significant insurance hikes or accessibility issues tomorrow.
Beachfront buyers must also contend with the Coastal Construction Control Line (CCCL). This regulatory boundary protects the dune system and dictates exactly how and where you can build or renovate. Zoning laws add another layer of complexity. If you plan to offset your mortgage with short-term rentals, you'll find New Smyrna Beach has vastly different restrictions compared to Ormond Beach. Verify these local ordinances before you commit to a contract; assuming they are uniform across the county is a tactical error.
Reading a FEMA flood map for properties in Port Orange or Deltona is a non-negotiable skill. As FEMA continues to phase in risk-based pricing, your premium will depend on more than just your zone. Secure an elevation certificate during your due diligence period to determine the home's height relative to the base flood elevation. This document is your most powerful tool for negotiating insurance costs and assessing true risk. If you are looking for a strategic advantage, utilize our AI-powered property search to filter for homes with favorable elevation profiles.
The 50% Rule states that if a structure in a special flood hazard area is damaged or improved by more than half of its market value, it must be brought into full compliance with current floodplain management regulations.
Daytona Beach is famous for its high-rise condos and gated communities, each governed by strict associations. Review the association's financials with precision. A low monthly fee might hide a lack of reserves, leading to a sudden, five-figure special assessment for roof repairs or elevator maintenance. Investigate pet weight limits and parking restrictions early; discovering your truck doesn't fit in the garage or your dog exceeds the weight limit after closing is an avoidable disaster. Finally, account for estoppel fees in your closing costs. These fees cover the administrative cost of verifying your standing with the association and are a standard part of the Volusia County closing process.
Stop letting a designer's eye dictate your largest financial decision. One of the most common first time home buyer mistakes to avoid is prioritizing aesthetic staging over the property’s structural integrity. Sellers in Volusia County often use high-end furniture and neutral paint to distract from aging "bones" like cast-iron pipes or a roof nearing the end of its life. While a home in DeLand might appear to be a bargain, failing to analyze hyper-local market trends could leave you with a depreciating asset. Data must lead; emotion should only follow once the numbers prove the value.
Relying on national real estate portals is a strategic error. These platforms often lag behind the local Multiple Listing Service (MLS), showing properties as active when they are already under contract. With a median of 45 days to pending in Volusia County, speed is your primary currency. Searching alone also means you miss out on off-market opportunities and "pocket listings" that never reach the public. You need a proactive approach that utilizes real-time data to identify value before the competition even knows it exists.
Our AI-Powered Property Search identifies emerging neighborhood value in cities like Orange City and DeBary before the trends become obvious. While standard apps provide basic filters, our smart algorithms analyze historical price movement and inventory levels to predict which areas are poised for growth. This technology allows you to beat other buyers to new listings by delivering alerts the second a property hits the market. You can filter for absolute "must-haves" with surgical precision, ensuring your search remains efficient and focused on high-performance assets.
Professional market analysis mirrors an appraiser's methodology. We don't just look at what a house is worth; we analyze why it's priced that way. By comparing comparable sales (Comps) with a critical eye, we identify whether a listing is truly a "good deal" or an overpriced liability. We also track the 27% of listings currently seeing price cuts to gauge seller motivation. Understanding these metrics allows you to negotiate from a position of strength. Local expertise beats a generic algorithm every time because it accounts for the nuances of specific Volusia County streets and subdivisions.
Don't let the pressure of a competitive offer cloud your judgment. Waiving your right to an inspection is one of the most reckless first time home buyer mistakes to avoid, even in a fast-moving market. A standard inspection typically costs between $378 and $513 in Florida. This is a minor investment compared to the risk of discovering a failing roof or faulty wiring after the keys are in your hand. Beyond the general report, you must verify the permit history for any additions, pool installs, or major electrical upgrades. Unpermitted work in Volusia County can lead to insurance cancellations or expensive municipal fines that become your responsibility the moment you close.
Negotiation requires a balance of assertiveness and data. While it's tempting to fight for every minor cosmetic fix, over-negotiating small issues like chipped paint or dated fixtures can alienate a seller and kill the deal. Focus your leverage on structural, safety, and system-wide concerns that impact the home's long-term value. With 27% of Volusia County listings currently seeing price cuts, you have more room to negotiate than in previous years, provided you prioritize the right issues.
Approach your due diligence with a methodical mindset. Secure a comprehensive home inspection immediately after your offer is accepted. This serves as your baseline for negotiation. Next, request specialized tests for Wood Destroying Organisms (WDO) and mold, which are prevalent in our humid climate. A clean WDO report is often a lender requirement in Florida.
Negotiation is about strategy, not just price. In competitive markets like New Smyrna Beach, using an "Escalation Clause" allows your offer to increase automatically up to a certain limit if a higher bid comes in. This keeps you in the running without overpaying from the start. You should also prepare for "Appraisal Gaps." If the bank's valuation comes in lower than your offer price, having a plan to cover that difference can make your bid more attractive to sellers who fear a deal falling through.
Your Earnest Money Deposit (EMD) is another powerful signal. A higher EMD demonstrates serious intent and financial stability, often carrying more weight than a slightly higher purchase price. To master these tactical moves and secure your investment with precision, partner with a strategic advocate from our team today.
Hiring a friend or family member simply because they possess a real estate license is among the most frequent first time home buyer mistakes to avoid. This is a high-stakes business decision. It requires a specialist, not a casual acquaintance. A transactional agent simply facilitates paperwork and opens doors. In contrast, a strategic partner acts as a proactive advocate. They utilize deep market data to protect your equity and identify risks before they manifest. You need an expert who understands that your first purchase is the foundation of your future wealth.
Volusia County is not a monolithic market. It consists of 16 distinct cities, each with unique regulations and neighborhood personalities. The strategy required to secure a historic home in DeLand differs significantly from the approach needed for a high-rise condo in Daytona Beach Shores. Only a local expert with decades of experience can navigate these nuances with the precision your investment deserves. Don't settle for a generalist when you can have a master of the local landscape who knows every street from Ormond Beach to Ponce Inlet.
Led by Broker Walter Borgen, who has been active in the market since the 1990s, our team provides a signature level of service. As part of the REMAX Signature network, we blend historical context with modern methodology to ensure you never overpay. We don't just find houses; we optimize value. By leveraging advanced technology, we help you discover waterfront estates or inland retreats before the general public even knows they are available. Whether you target the surf-side lifestyle of New Smyrna Beach or the quiet acreage of De Leon Springs, our guidance remains tailored to your specific objectives.
Success in 2026 requires immediate, decisive action. Follow this roadmap to secure your position in the market:
Your journey to homeownership should be efficient and rewarding. By choosing a partner with market mastery, you eliminate the anxiety of the unknown. Take the first step toward a successful purchase by aligning with a team that prioritizes your results above all else.
Entering the 2026 real estate market requires more than just ambition; it demands a tactical advantage. You now understand that accounting for the specific costs of Florida homeownership and performing rigorous environmental due diligence are non-negotiable steps. Identifying the most common first time home buyer mistakes to avoid ensures you don't overpay for a property with hidden defects or unpermitted additions. Whether you're targeting a beachside condo or a suburban retreat, your success depends on moving faster and with more precision than the average buyer.
The Borgen Team of REMAX Signature brings deep roots in Daytona Beach real estate and cutting-edge AI-powered search technology to your side. We act as your strategic advocate, navigating the complexities of local zoning and insurance reassessments with professional mastery. Don't leave your largest financial decision to chance or a generalist agent. Secure your first home with Volusia County's local experts. Contact The Borgen Team today. You're fully equipped to turn your Florida homeownership goals into a definitive success.
The most significant error is failing to budget for the "Florida Factor," which includes high homeowners insurance premiums and property tax reassessments. Many buyers only look at the principal and interest. This is a classic first time home buyer mistakes to avoid because it leads to immediate financial strain. You must account for the $4,800 average annual insurance premium and potential flood insurance costs to ensure your long-term solvency.
Purchasing a home with a lower credit score is possible, though it directly impacts your interest rate. FHA loans typically accept scores as low as 580 with a 3.5% down payment. However, with 30-year fixed rates averaging 6.98% as of September 2026, a higher score secures much better terms. Focus on improving your debt-to-income ratio to offset a lower score and present a stronger profile to local lenders.
Your target savings should reflect the median home value in Volusia County, which reached $327,100 in late 2026. While FHA loans require 3.5% down, approximately $11,448, conventional programs for first-time buyers may require as little as 3%. Don't forget to set aside an additional 2% to 5% for closing costs. This ensures you have sufficient liquidity to finalize the deal without depleting your essential emergency reserves.
A Wind Mitigation inspection verifies how well your home resists high-wind events and hurricanes. It's a critical step in the Florida insurance process because it qualifies you for significant premium discounts. The inspector checks your roof's shape, age, and attachment methods, along with window and door protections. Skipping this report is a costly error that results in paying much higher annual insurance rates than necessary for your property.
Volusia County residents have access to robust state-level assistance. The Florida Hometown Heroes program offers up to 5% of the mortgage amount, capped at $35,000, for eligible frontline workers. Additionally, the Florida Assist program provides up to $10,000 as a zero-interest, deferred second mortgage. These programs are designed to bridge the gap for buyers who have the income to support a mortgage but lack the upfront capital for closing.
If the appraisal is lower than your offer, an "appraisal gap" occurs. Lenders only provide financing based on the appraised value, not the contract price. You can cover the difference in cash, negotiate a price reduction with the seller, or exercise your appraisal contingency to cancel the contract. In a market where 27% of listings show price cuts, sellers are often more willing to renegotiate to keep the deal moving.
Choosing between a condo and a single-family home depends on your lifestyle and financial goals. Condos in Daytona Beach Shores offer lower maintenance but come with HOA fees and the risk of special assessments. Single-family homes in DeLand provide more privacy and full control over property improvements, which can build equity faster. Analyze the total monthly cost, including association dues and insurance, before deciding which asset class fits your strategy.
The typical home buying journey in Florida spans 30 to 60 days from contract to closing. Financing is the primary variable; most lenders require at least 30 days to process a mortgage. Cash transactions in cities like Port Orange can close in as little as two weeks. Your timeline also depends on the inspection period and the speed of the title search, so staying organized is essential for a smooth transition.
Walter Borgen has lived in the Daytona Beach area for most of his life. Walter started his real estate career in his early 20s as a part time wholesale real estate investor. Quickly Walter became fa....
Did you know that 27% of Volusia County listings currently feature price cuts, yet many buyers still overpay because they lack a data-driven strategy? Entering the 2026 market in Daytona Beach or
Are you unknowingly overpaying your property taxes while your neighbors enjoy massive savings? In the fast-moving Florida real estate market, missing a single detail in your filing can cost you
Will your dream home turn into a tax nightmare after your first year of ownership? Most buyers rely on outdated listing data, only to face a massive escrow shortfall when the county reassesses their
Ask a couple people how the housing market is doing and you’ll probably get a couple different answers. That’s because right now, the market runs on 2 very different tracks, split by
 Copyright © MFRMLS.com All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumers personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. Information on this site was last updated Last updated on September 16, 2026 1:23 PM UTC The listing information on this page last changed on Last updated on September 16, 2026 1:23 PM UTCd. The data relating to real estate for sale on this website comes in part from the Internet Data Exchange program of MFR MLS.
All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumers personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing.
Updated on September 16, 2026 1:23 PM UTC
33. Required DMCA Notice
The Digital Millennium Copyright Act of 1998, 17 U.S.C. §512, the DMCA, provides recourse for copyright owners who believe that material appearing on the Internet infringes their rights under U.S. copyright law. If you believe in good faith that any content or material made available in connection with our website or services infringes your copyright, you (or your agent) may send us a notice requesting that the content or material be removed, or access to it blocked. Notices must be sent in writing by email to DMCAnotice@MLSGrid.com. The DMCA requires that your notice of alleged copyright infringement include the following information: (1) description of the copyrighted work that is the subject of claimed infringement; (2) description of the alleged infringing content and information sufficient to permit us to locate the content; (3) contact information for you, including your address, telephone number and email address; (4) a statement by you that you have a good faith belief that the content in the manner complained of is not authorized by the copyright owner, or its agent, or by the operation of any law; (5) a statement by you, signed under penalty of perjury, that the information in the notification is accurate and that you have the authority to enforce the copyrights that are claimed to be infringed; and (6) a physical or electronic signature of the copyright owner or a person authorized to act on the copyright owners behalf. Failure to include all of the above information may result in the delay of the processing of your complaint.
 Information is deemed to be reliable, but is not guaranteed. © 2026 MLS. Last Updated September 16, 2026 12:58 PM UTC The information on this sheet has been made available by the MLS and may not be the listing of the provider. Listing data provided by the Daytona Beach Area Association of REALTORS® Internet Data Exchange (IDX) program. Data is believed to be accurate but not warranted.
 New Smyrna Beach Board of REALTORS® All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested
in purchasing. The data relating to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than The Signature Sales Team may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 16, 2026 1:40 PM UTC
Show More...
